
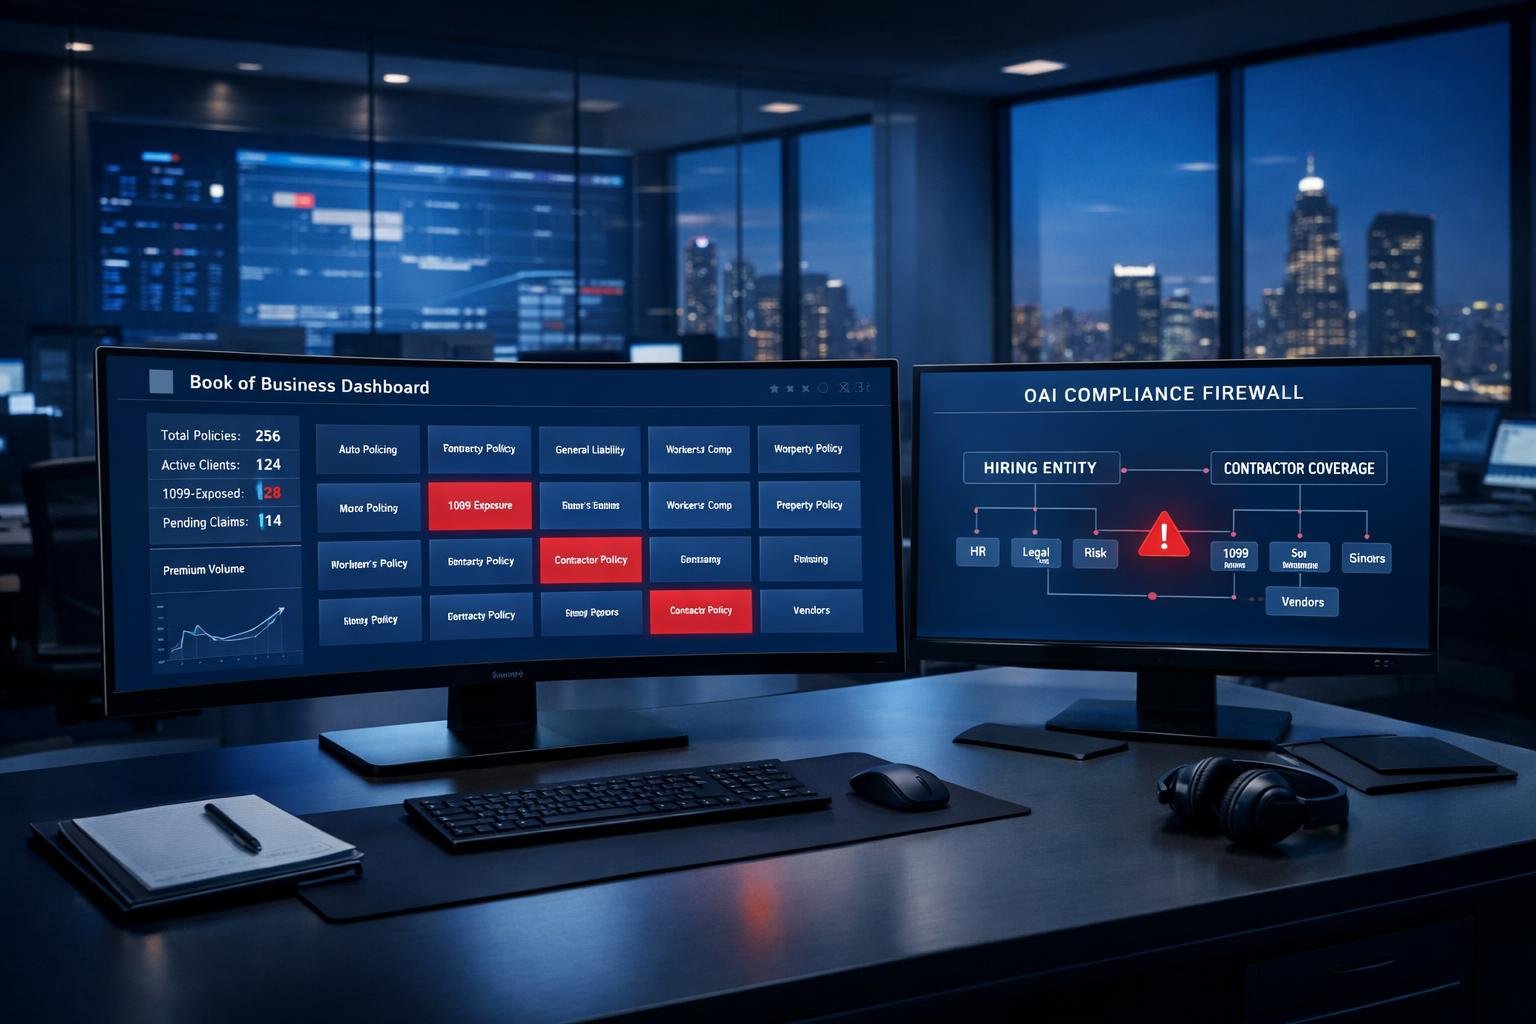
Every seasoned agent sits on a goldmine of commercial clients who are quietly exposed to 1099 misclassification risk. The ability to cross-sell occupational accident insurance into that existing book is the single highest-leverage revenue play available to commercial producers in 2026. No new prospecting. No cold outreach. Just a structured conversation with clients who already trust you — and already write premium with your agency every year.
This is the playbook for turning your existing general liability, commercial auto, and BOP book into a recurring occupational accident insurance (OAI) pipeline. By the end of this guide, you will have a repeatable framework for identifying qualified clients, handling the conversation, and writing monthly premium that the insured pays directly — not your agency.
The Hidden OAI Opportunity in Every Commercial Book
If you write commercial insurance, you already have OAI prospects sitting in your CRM. Any client who issues a 1099 to a worker — a trucking carrier contracting owner-operators, a home healthcare agency using travel nurses, an IT consultancy farming out projects to independent developers, a last mile delivery company running contract drivers — is legally exposed every time that contractor gets hurt on the job.
The exposure is not theoretical. Under the Department of Labor’s current Independent Contractor Rule and the economic realities test, a 1099 worker who is injured and cannot work can pursue two paths simultaneously: a direct claim against the hiring entity, and a misclassification complaint that can retroactively convert the worker into a W-2 employee. The second path is the one that bankrupts businesses.
Your client assumes their general liability policy handles it. It does not. GL covers third-party bodily injury and property damage — not the injury of the contractor themselves. Workers’ compensation does not apply either, because W-2 employees receive Workers’ Compensation; 1099 independent contractors receive Occupational Accident Insurance. They are legally distinct coverage types for legally distinct worker classifications, and the gap between them is where audits are born.
The 3-Question Cross-Sell Test
Before you pitch anything, you need a fast way to qualify which clients in your book are OAI candidates. Use these three questions on every commercial renewal call:
- Do you issue any 1099s to workers who perform services for your business? If yes, keep going. If no, move on.
- Do those 1099 workers carry their own occupational accident policy that names your business as a certificate holder? In our experience, fewer than 10% do.
- If one of them got hurt tomorrow, whose insurance pays? This is the silence-inducing question. Most business owners have no answer.
If the client issues 1099s and cannot answer question three, they are an OAI prospect. Full stop. The compliance exposure exists regardless of whether they acknowledge it — and your job as their agent is to surface the gap before a DOL auditor, plaintiff’s attorney, or injured contractor does it for you.
Where to Find the 1099 Signal in an Existing File
The fastest place to identify 1099-heavy accounts is the prior policy’s description of operations and the loss run. Look for language like “subcontracted drivers,” “independent practitioners,” “per diem clinicians,” “independent delivery agents,” or “outside consultants.” Each of those phrases is a buried OAI signal that most producers walk past on renewal.
Cross-Sell Occupational Accident Insurance as a Compliance Firewall
Cross-selling occupational accident insurance is not a premium-push conversation. It is a compliance-protection conversation, and compliance sells faster than price in 2026’s regulatory climate.
Frame the policy as a Compliance Firewall — a documented layer of coverage that sits between the hiring entity and the contractor. When an auditor opens an investigation into worker classification, one of the first questions they ask is: “Does this contractor have coverage that treats them as genuinely independent?” An OAI policy in the contractor’s name, paid through a pay-as-you-go billing structure where the hiring entity does not control the worker’s tools, schedule, or method of work, is a strong signal of genuine independence.
Without that firewall, the hiring entity has nothing to show an auditor except a 1099 and a verbal agreement. With it, they have a paper trail that treats the worker as an independent business, reducing the likelihood of a misclassification finding. For deeper context on how these investigations unfold, see our guide on 1099 Protect compliance resources.
The Revenue Math Every Agent Misses
Traditional commercial coverage pays agents an upfront commission and a smaller renewal hit a year later. OAI is different, and the difference is where agents make real money.
The WORK Program operates on a monthly, pay-as-you-go billing structure. Premium accrues based on actual contractor activity, not a guessed annual estimate. Agents receive recurring commission every month that policy stays in force — not once a year, not after a painful audit reconciliation. For agencies with commission-hungry producers, this flips the economics of the book.
Run the numbers on a typical mid-size trucking carrier with fifteen owner-operators: monthly premium on an OAI program often falls between $1,200 and $3,500 depending on miles and routes. At standard commission splits, that is recurring monthly revenue from a single account — often more than the entire GL policy on the same insured. Multiply that across your book’s 1099-heavy accounts and the math becomes obvious.
Add in the fact that the 3% credit card and ACH processing fee can legally be passed directly to the insured, and the agency writing OAI is not losing a cent of processing margin. It is a coverage line that behaves more like a recurring subscription than a traditional insurance policy.
How to Pitch OAI in 90 Seconds
Once you have qualified the client with the three-question test, your pitch is not a product sales monologue. It is a compliance question followed by a solution. Use this structure:
“Based on what you just told me, if one of your 1099 contractors got injured tomorrow, you are sitting on a jurisdictional exposure that your current coverage does not address. Two things can happen: they file against your general liability, which is going to deny the claim because a contractor injury is not a third-party injury. Or — and this is the one that closes businesses — they file a misclassification complaint with the DOL and argue they were functionally an employee. That becomes back wages, unpaid taxes, and penalties you never reserved against.”
“We can close that gap with an occupational accident policy in the contractor’s name. Monthly billing, the contractor pays it, and you finally have documentation that treats them as an independent business. It protects you from the classification audit and protects them if they ever get hurt. Can I put together a quote this week?”
Notice what the pitch does not do: it does not compare OAI to Workers’ Compensation, because the two are not substitutes. W-2 employees receive Workers’ Compensation; 1099 contractors receive Occupational Accident Insurance. Confusing the two is the single fastest way to lose credibility with a business owner who has already been through a classification scare.
Handling the Most Common Objection
The objection you will hear most often is: “My contractors should carry their own coverage.” The correct response is that most of them do not, and as the hiring entity, the client carries the exposure regardless of what the contract language says. Offering to facilitate coverage in the contractor’s name — billed monthly — is the cleanest path to closing the compliance gap without creating a payroll relationship that itself looks like employment.
Start With Your Next Five Renewal Calls
You do not need a new list, a new marketing budget, or a new prospecting script. You need a three-question filter and a willingness to ask the compliance question on every renewal for the next thirty days.
Pull a list of your top five commercial renewals for this month. For each one, check whether they issue 1099s — the answer is often buried in the loss run or the prior policy’s description of operations. Run the three-question test on the call. Quote the ones that qualify.
That alone, repeated across a producer team, converts an existing book into a recurring OAI pipeline without adding a single new name to the database. To quote a client or request agent appointment materials, visit 1099 Protect and start the producer onboarding. The book is already there. The premium is already there. The only thing missing is the conversation.